Investment tax: what the broker withholds and what you declare
Who is responsible for the tax?
“The broker withheld my tax. Do I need to do anything else?” It depends on the income we are talking about. Dividends and capital gains are taxed differently, and a tax withheld abroad do not automatically close the discussion with ANAF.
First: two different incomes
Dividend this is the part of the profit that the company distributes to its shareholders. Profit from sale it is basically the positive difference between the selling price and the acquisition value, adjusted for eligible costs. The exact calculation depends on the instrument and the applicable tax regime.
The same actions can bring you both types of income, taxed separately. Capital gains are not taxed as long as you do not sell, but dividends received in the meantime are taxed.
Dividends from a Romanian company
If the company is a tax resident in Romania, it calculates, withholds and pays the tax. As a general rule, the tax is calculated and withheld when the dividend is paid. If dividends have been declared but not paid by the end of the year, the company owes the tax by January 25 of the following year.
For dividends distributed from January 1, 2026, the rate is 16% of the gross dividend. For the beneficiary, the income is considered realized on actual collection.
For a gross dividend of 1,000 lei, the tax is 160 lei, leaving 840 lei before any fees and CASS. The tax is final, so you do not file the Single Declaration for it. The CASS obligation is checked separately.
Don't forget: when the tax rate changes, the applicable rate at dividend distribution date, not on the date they are paid.
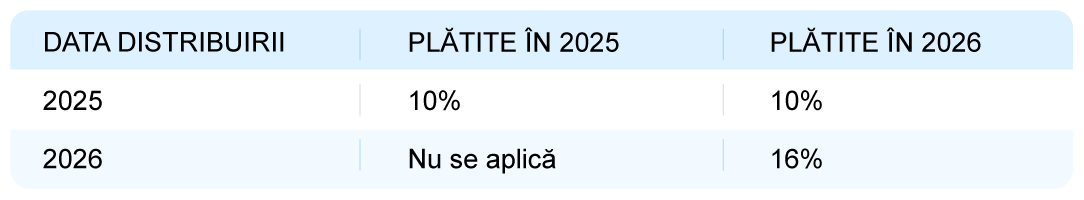
Dividends distributed in 2025 and paid in 2026 remain taxed at 10%. However, dividends from the 2025 profit, distributed by the EGMS resolution in 2026, are taxed at 16%. Dividends distributed based on interim financial statements prepared in 2025 retain the 10% rate, without recalculation at the annual adjustment.
Dividends from a foreign company
Here it matters tax residency the company paying the dividend, not the broker's country, the account currency, or the exchange. Distribution date, proven by the payer's or intermediary's documents, establishes the Romanian quota, and the year of collection establishes the year of declaration.
A dividend distributed in 2025 and received in 2026 remains subject to the 10% rate in Romania and is declared as income earned in 2026. For a dividend distributed and received in 2026, the Romanian tax is 16% of the gross amount.
If tax was withheld abroad, you may benefit from a foreign tax credit if the applicable convention provides for this method. The credit applies to the actual foreign tax paid and is calculated separately for each country and type of income.
Example: for a gross dividend of 1,000 lei, the Romanian tax is 160 lei. If 100 lei were withheld abroad and are eligible, you pay an additional 60 lei in Romania, not another 160. The credit cannot exceed the Romanian tax on the income, and the Single Declaration remains mandatory even if it fully covers it.
Keep the documents regarding the gross dividend and the foreign tax. Amounts in foreign currency are converted into lei at the BNR annual average exchange rate of the year the income was earned.
Gain from the sale of shares, ETFs or fund units
Here the question changes: the entity you contracted with log in to Romanian withholding tax regime? The regime covers intermediaries and management entities provided by the Fiscal Code, Romanian tax residents, and non-residents who have a permanent establishment in Romania acting as intermediaries.
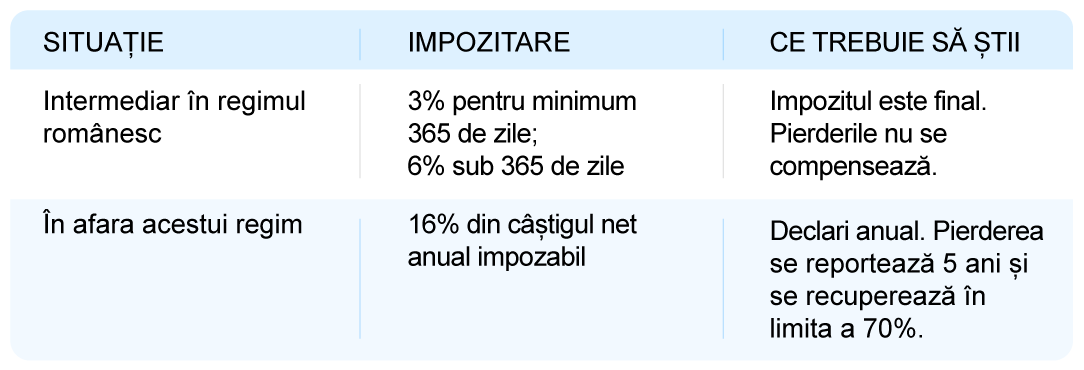
First, check the intermediary's status. Only if they fall under the Romanian withholding tax regime does the holding period determine the 3% or 6% rate. In other words, you do not start directly from the holding period but from the entity you have the contract with.
If yes, the intermediary withholds 3% from each gain for securities held for at least 365 days or 6% for a shorter period. The tax is final, and losses under this regime no offsetting with earnings.
If not, calculate and declare the annual taxable net gain, on which is applied 16%. The annual tax loss is carried forward 5 years consecutive and are recovered up to 70% from the annual net earnings from the same source, according to the applicable rules.
Don't forget: losses from sales do not reduce the dividend tax.
Check the entity you have contracted with and its tax information. It is not enough that the website or app is in Romanian or that you can fund the account in RON.
Withholding tax does not automatically mean "nothing to declare"
CASS is a separate obligation. Relevant income from investments is combined with income from rents and other categories provided by law. The salary is not credited in this calculation, and the fact that you pay CASS from your salary does not automatically exempt you from CASS on investments.
For sales with withholding tax, for the ceiling you add up the profits from profitable transactions reported by the intermediary. You do not deduct losses from other transactions. The rule concerns the withholding regime, not the calculation of the annual net gain from self-assessment.
For dividends, the amounts paid, reduced by the withheld tax, are taken into account for the ceiling. The foreign tax credit can reduce the Romanian income tax but is not deductible from CASS.
If the relevant total reaches at least 24,300 lei In 2026, you owe CASS and file the Single Declaration, unless a legal exception applies. CASS it is not 10% of the total gain, it is calculated on one of the fixed bases below.
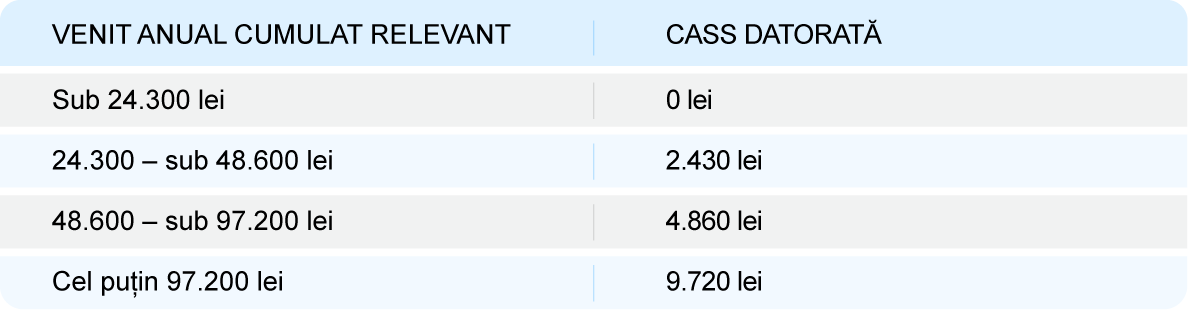
Example: you have earnings of 30,000 lei and losses of 20,000 lei, all from transactions with withholding tax. For the ceiling, it counts 30,000 lei, not 10,000 lei. Without other relevant income or legal exceptions, you owe 2,430 lei CASS.
What you should remember
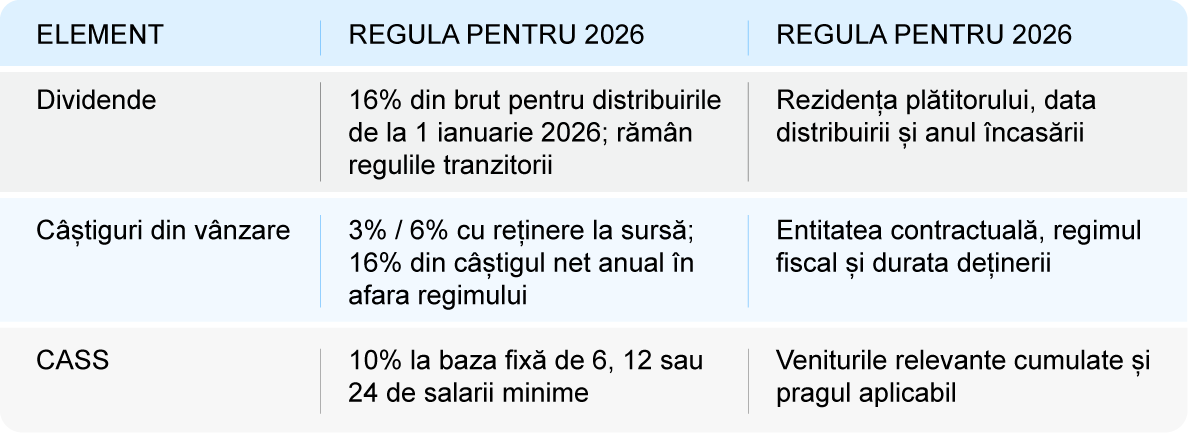
The term provided by the current rules is May 25, 2027 for declaring income earned in 2026 and paying tax/CASS through the Single Declaration. Form D212 and the instructions must be rechecked upon publication.
La CASS, reperul pentru 2026 este 4.050 lei, salariul minim de la 1 ianuarie.
Legal basis and notice
Law no. 227/2015 regarding the Fiscal Code, with subsequent amendments and completions; Law no. 141/2025; Law no. 239/2025; GEO no. 128/2024; GD no. 1,506/2024; GD no. 146/2026; The methodological norms approved by GD no. 1/2016.
Educational material created by The Tax Institute together with Banca Transilvania. It does not constitute tax, legal, or investment advice and does not represent a recommendation to buy, sell, or hold. The information reflects legislation verified as of September 23, 2026. For a specific situation, consult a specialist. Material for individuals tax resident in Romania. Material for individuals tax resident in Romania. The examples concern portfolio investments; special cases are analyzed separately.
The Tax Institute is the first Romanian think tank dedicated to taxation. It brings together experts in taxation, law, economics, academia, and public policy, contributing to the improvement of tax policies through data-driven analyses, impact assessments of tax measures, and dialogue among specialists, the business community, and policymakers. An important focus of its activity is tax education and translating complex tax information into language accessible to the general public. More at www.taxinstitute.ro